

Autopilot - Investment App

- 1.10K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Autopilot - Investment App from Appgk
I approached Autopilot as a finance app rather than as a shortcut to effortless wealth. That distinction matters. Its promise is appealing: make investing feel more modern and less intimidating, especially for someone who does not want to spend every evening comparing funds, reading market commentary, or learning a complicated trading interface. My experience is that the app is most interesting when viewed as a guided investing tool, not as a replacement for understanding where your money goes.
Autopilot is free to download, aimed at everyone, and developed by Autopilot Holdings Corporation. It belongs to the finance category and has built a sizeable audience, with over one million installs, a 4.7 average from around 7,400 ratings, and roughly 1,100 written reviews. Those figures suggest that many people find the basic idea approachable, although popularity alone should never be treated as proof that an investment app is suitable for every financial situation.
The app was released on November 15, 2023, and the current version is 1.19.23. It requires Android 10 or later. I would check those requirements before planning to use it on an older phone, particularly if the device is also used for banking or authentication. The practical question is not simply whether Autopilot looks modern, but whether its choices, account controls, and data-related prompts give you enough confidence to use it responsibly.
What using Autopilot feels like when trust matters
My first impression is that Autopilot tries to reduce the emotional load of investing. Traditional brokerage apps often place charts, tickers, order types, and market movements in front of you immediately. That can be useful for an experienced investor, but it can also encourage impulsive decisions. A more guided approach can help a beginner pause and think about the purpose of an investment instead of reacting to every market move.
Best Parts of Autopilot - Investment App
Things to Keep in Mind About Autopilot - Investment App
That convenience comes with a trade-off. Whenever an app makes investing feel simpler, I become more interested in the decisions happening behind the simple screen. A clean interface can hide important choices just as easily as it can remove unnecessary confusion. Before committing funds, I would want to understand what an investment action means, whether it can be changed, how quickly I can stop or adjust it, and what information the app asks me to share along the way.
This is where Autopilot should be judged differently from a normal budgeting app. A budgeting tool can help you categorize spending without directly changing your investment position. An investing service sits closer to real money decisions. I therefore recommend treating every confirmation screen as meaningful, even if the wording feels friendly and the process takes only a few taps.
News and Features Related to Autopilot - Investment App

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
For a new investor, that slower approach is not a disadvantage. In fact, I think one of the best ways to use the app is to create a short personal checklist before connecting an account or approving an investment-related action. I would write down the goal, the amount I can genuinely leave invested, and the condition that would make me stop. This keeps the app from becoming the decision-maker by default.
Account controls deserve more attention than visual polish
When I evaluate a finance app, I look for visible user choices rather than assuming that a polished design means strong control. The important questions are practical: Can I review what I am authorizing before I confirm it? Can I identify connected accounts? Can I change an instruction without contacting support? Can I tell whether an action is pending, completed, or still waiting for attention?
Don't want to read the full review?
Those are not decorative details. They determine whether the user remains in charge after the initial setup. Autopilot is more suitable for someone who is willing to open each relevant screen and understand the available controls. I would not connect an account while distracted, and I would not approve an investment simply because the app presents it as the next obvious step.
A useful routine is to inspect the app after setup rather than waiting for a problem. Review the account area, note how changes are presented, and check whether notifications or prompts clearly distinguish information from an action request. If you see a request that affects money, stop and read it separately from the surrounding explanation. This small habit reduces the chance of approving something because the interface feels reassuring.
Screenshots
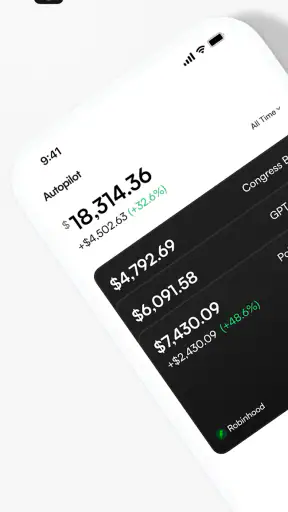
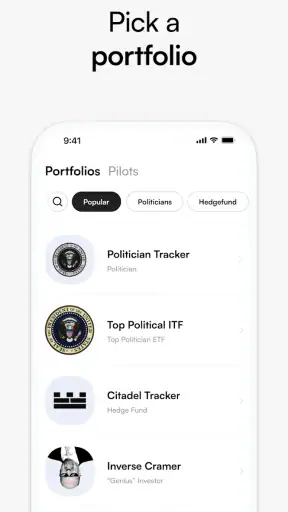
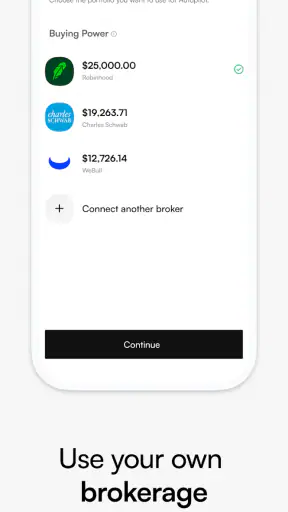
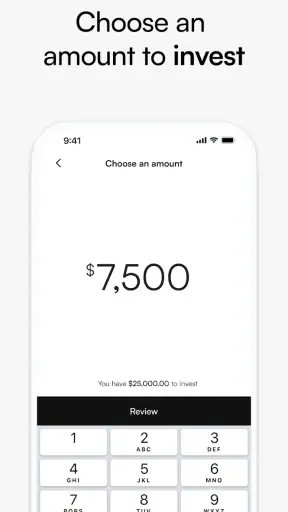
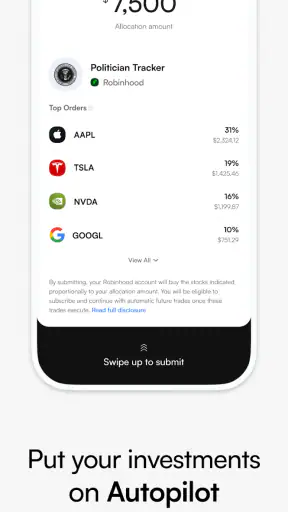
I also recommend keeping a simple personal record of the choices you make in Autopilot. It does not need to be complicated. The date, purpose, amount, and reason for the decision are enough. This gives you a reference if you later wonder why a position exists or whether a recurring instruction still matches your circumstances.
Privacy decisions should happen before convenience takes over
Finance apps naturally involve sensitive moments. You may be asked to identify yourself, connect an account, review financial information, or approve access needed for the service to work. I do not treat those prompts as routine just because they appear during onboarding. I read the explanation, look at the permission or connection choice, and consider whether I understand what I am agreeing to.
My rule is simple: if I cannot explain in plain language why an access request is needed, I pause. That does not automatically mean the request is inappropriate; it means I should not approve it on autopilot. I also avoid setting up an investment account while using an unfamiliar network or a shared device. The safest workflow is one where I can concentrate and verify every screen.
There is a useful difference between information that helps the app provide a service and information that merely improves convenience. I would pay attention to that distinction whenever Autopilot presents a choice. If a prompt offers an optional setting, I would decide whether the benefit is worth the additional sharing rather than accepting the default without reading it.
After setup, I would revisit the app’s account and privacy areas occasionally. Financial apps can change their screens as versions evolve, and a setting that was easy to miss during onboarding may become important later. The current version is 1.19.23, so keeping the app updated is sensible, but an update should not be treated as a reason to skip reviewing new prompts or revised choices.
One practical tip is to separate identity verification from investment enthusiasm. Finish the security and account steps first, then close the app and return later to consider the investment decision. That gap helps prevent the momentum of registration from carrying you into a financial commitment you have not properly evaluated.
A realistic everyday use case
Imagine someone who receives income monthly, has already handled essential bills, and wants to begin investing without watching the market throughout the day. Autopilot may fit that person if the app’s guided approach makes it easier to follow a deliberate plan. The user could set aside an amount that does not interfere with rent, debt payments, emergency savings, or near-term expenses, then review the investment choices with a long-term mindset.
The important part is the order of operations. I would not open the app after a stressful day, see a market-related prompt, and make a decision based on fear of missing out. I would decide the amount away from the screen, confirm that the money is genuinely available, examine the action inside the app, and keep a record of what I approved. That workflow turns the app into a tool for carrying out a plan rather than a source of pressure.
Autopilot may also appeal to a busy person who understands that doing nothing indefinitely is not a plan, but who does not want the complexity of a full trading platform. The advantage is reduced friction. The limitation is that reduced friction can make an unsuitable decision feel easy too. The user still needs to understand risk, time horizon, and the possibility that investments can lose value.
For a couple managing shared finances, I would be more cautious. A personal investing app may not automatically provide the visibility or shared approval process that both people expect. Before using it with household money, I would agree on who can authorize actions, how records will be kept, and what happens if one person wants to change the plan. If those controls are not clear in the app, a more traditional arrangement may be easier to manage.
Where it differs from conventional investing apps
Compared with a conventional brokerage app, Autopilot’s appeal is likely the guided experience suggested by its name and positioning. A brokerage usually gives you broader direct control, more visible market information, and more responsibility for choosing and managing investments. That is useful when you already know what you want, but it can be overwhelming when every decision is unfamiliar.
Compared with a bank’s investing section, Autopilot may feel more focused on the investing journey rather than being one feature among checking, savings, cards, and loans. A bank can be convenient because your financial life is already in one place. On the other hand, a dedicated app may be easier to approach when you want to concentrate on one goal. The better choice depends on whether simplicity or consolidation matters more to you.
Compared with a spreadsheet and manual transfers, an app can save time and make a routine easier to follow. The spreadsheet has one major strength, though: it forces you to see the assumptions and numbers yourself. I would use a simple personal record alongside Autopilot, especially during the first few months. That gives me an independent view instead of relying entirely on the app’s presentation.
Compared with a human financial adviser, Autopilot is less personal by nature. A person can discuss unusual income, family responsibilities, tax concerns, debt, and competing goals in context. If your situation is complicated or a mistake would be costly, professional advice may be more appropriate than relying on an app, however approachable the interface may be.
Who should use it, and who should wait
I see Autopilot as a reasonable candidate for a beginner who wants a less intimidating entry into investing and is prepared to remain involved in the decisions. It may also suit an experienced user who values a streamlined workflow for a clearly defined purpose. In both cases, the user should be comfortable reading confirmations, checking account access, and accepting that investment results are not guaranteed.
I would be cautious about recommending it to someone who needs money soon, has no emergency cushion, or is hoping for quick profits. A modern interface cannot remove market risk. It also should not be used as a substitute for paying attention to high-interest debt or essential financial obligations. If the money is needed for a near-term bill, it should not be treated as available simply because the app makes investing easy.
I would also suggest skipping it for now if you want detailed control over every trade, advanced analysis, or a highly customized portfolio process. A full brokerage platform may serve you better in that situation. Likewise, if you need joint oversight, specialized account arrangements, or personal guidance, compare those needs against what you can visibly manage inside the app before opening an account.
Small habits that make the experience safer
My strongest recommendation is to separate discovery from commitment. Explore the interface first, read the explanations, and identify the screens that control money. Do not connect an account or approve an investment just to see what happens. If the app does not make a choice understandable, that is a reason to pause, not a reason to tap through faster.
Second, use a fixed review day rather than checking constantly. A set routine can reduce emotional reactions to market movement and makes it easier to notice whether your original plan still fits. I would review the purpose of the account, the amount involved, and any pending actions. I would not turn every notification into a reason to change course.
Third, keep contact and security details current. A finance app is only as usable as your ability to regain access and recognize legitimate prompts. I would avoid sharing sign-in information, use the device’s available security protections, and treat unexpected requests for sensitive information with suspicion until I have verified where they came from.
Finally, I would test my own understanding by explaining the account to a friend in one minute. What is the goal? What action is being taken? What could go wrong? What would I do if my circumstances changed? If I cannot answer those questions, I am not ready to increase the amount involved.
My cautious verdict
Autopilot presents a compelling route into investing for people who are put off by traditional brokerage interfaces. Its free availability, broad age rating, and modern positioning make it approachable, while its strong user response suggests that the concept resonates with a substantial audience. I like the idea of reducing needless complexity, particularly for someone who needs help turning an intention into a consistent financial routine.
Still, I would not confuse an easy workflow with a low-risk investment decision. The app deserves trust only when the user actively checks account controls, reads data-sensitive prompts, and understands each authorization. Those habits are especially important because the same simplicity that helps a beginner get started can also make it tempting to move too quickly.
My recommendation is therefore conditional but positive: try Autopilot if you want guided investing, have money you can leave invested, and are willing to verify every important choice. Start small, document your decisions, and compare its controls with your actual needs before relying on it for more of your financial life. If you need advanced trading tools, shared financial management, or personal advice, a conventional brokerage, bank service, or qualified adviser may be the better fit.
In the end, the app works best when it supports your plan rather than replacing it. The most valuable control remains the pause before you approve an action. If Autopilot helps you make that pause without burying the relevant choices, it can be a useful finance companion. If it encourages you to hand over judgment simply because the process looks effortless, I would step back and choose a more transparent option.
Autopilot - Investment App FAQ
What is Autopilot - Investment App and how does it work?
Autopilot - Investment App is designed to help users follow and manage investment strategies through a mobile interface. Depending on the available features and your region, the app may provide portfolio tracking, automated trade execution, strategy discovery, or notifications based on selected investors or market activity. Before using it, review exactly how automation works, what assets are supported, and whether trades require your approval.
Is Autopilot - Investment App safe to use with my money and investment account?
The app may connect with a brokerage or financial account to display information or carry out investment instructions, so security should be considered carefully. Check whether connections use trusted authorization methods, whether sensitive credentials are stored by the app, and what protections are provided by the linked broker. Never share passwords outside official login screens, and remember that security features cannot eliminate investment risk.
Does Autopilot automatically buy and sell investments for me?
Autopilot’s level of automation can depend on the strategy, account connection, and permissions you select. Some features may only track portfolios or send alerts, while others can place trades automatically after you authorize them. Read the order settings before activating a strategy, including position limits, rebalancing rules, timing, and the option to pause or disconnect automation if market conditions change.
Are there fees, subscriptions, or additional trading costs?
Before downloading or connecting an account, check the app’s current pricing information because costs can vary by plan, location, and feature availability. Possible expenses may include a subscription, premium strategy access, brokerage commissions, regulatory charges, spreads, or other transaction-related costs. A service advertised as commission-free can still involve indirect costs, so review both Autopilot’s terms and your broker’s fee schedule.
Is Autopilot - Investment App suitable for beginners?
The app may be convenient for beginners because it can simplify portfolio monitoring and provide an organized way to explore investment strategies. However, an easy interface does not make investing risk-free or guarantee returns. New investors should understand diversification, volatility, taxes, and potential losses before enabling automated actions. Start cautiously, use only money you can afford to lose, and verify every permission granted.











